Wattage and Tonnage
How Elon Musk spent seven years explaining bitcoin without ever endorsing it
Every quotation sourced and verified against a 186-item public timeline of Musk statements (2019–2026) · Not legal, tax, or investment advice.
The two sentences almost nobody read
On July 12, 2026, someone on X told Elon Musk that the future economy would be measured in energy. It was practically his own slogan repeated back to him — “energy is the true currency” is his sentence. He corrected it. The correction ran two sentences, invoked Einstein’s most famous equation, and drew a fraction of the attention of anything else he posted that week. But those two sentences completed something he has been assembling in public, one fragment at a time, since 2019: a complete theory of money. Assembled in order, the theory points at exactly one instrument. He names bitcoin freely enough — as an engineering fact, a comparison, an aside — but in seven years he has never once stated the conclusion, and never once cheered.
Before diving in, I want to highlight a piece of wisdom from an interview that had fewer than a hundred views when I found it. David Thayer, a Blackstone veteran — an insider explaining how insiders privately think — observed last fall that the most successful people in finance and investing master a single silo of expertise and lose the incentive to look outside it, “which as they progress in their career does not necessarily serve them well.” The remedy is not the accumulation of more information — “boiling the ocean,” he calls it — but deduction from “a fundamental framework within which to view the world... that being the Austrian economic school”: the tradition that treats prices as knowledge, money as something markets grow rather than governments decree, and central planning of either as the root error. A framework determines what a person is able to notice. Musk’s theory of money has flown past economists and bitcoiners alike because it fits no framework they were trained on. It fits this one.
This essay walks through the theory from first principles. Every Musk quotation is real and sourced; the full verified 186-item timeline is linked above. Every premise is his. The ordering, and the final step, are mine.
1. Money is a ledger
Start where he started, in March 2019, with a post written as literal computer code:

It passed for a programmer’s joke. It is the foundation of everything that follows. Money, it says, is not wealth. Money is a database — a ledger — whose job is to record who is owed what for their time.
A single example carries the idea. A man spends his day repairing his neighbor’s plumbing. Society now owes him a day’s worth of value, and the money he is paid is the record of that debt: a ledger entry stating that he contributed and has not yet collected. The real wealth is the goods themselves — the houses, the food, the energy. As Musk put it on Joe Rogan’s podcast, “If you don’t make stuff, there’s no stuff.” Money feeds no one; it records who may claim what. His own favorite illustration is blunter, a thought experiment about being shipwrecked on an island with a trillion dollars in the bank: “It’s worthless. You’d rather have a can of soup. You could have all the bitcoin in the world, and you’re still going to starve.” It is worth noticing what that sentence includes. He applies the rule to bitcoin as readily as to dollars. Money of any kind is only the ledger, never the wealth.
Seen this way, inflation loses its mystery. Inflation is corruption of the ledger: new entries written for those who did no work. When a government prints a trillion dollars, no new houses or food or energy come into existence; there are simply more claims chasing the same goods, and every existing claim quietly counts for less. It is a tax no one votes on, and it falls hardest on those who hold plain dollars — hourly workers, renters, savers. And the dilution is only the visible half of the damage. When claims can be created without work, the most talented people are gradually paid more to rearrange claims than to build things, and capital follows them. Part of the cost of a corrupted ledger appears in the price of bread. The rest never appears anywhere — it is everything that was never built.
One further detail of the 2019 post will matter later: “As automation++, value of money--.” As machines take over more of the work, money as we know it matters less. That clause is the destination of this entire essay.
2. How monetary competition is decided
Two years later, in January 2021, he replied to the bitcoin writer Robert Breedlove, with “#bitcoin” sitting in his profile bio:
If money is an information system, then the world’s monies — dollars, euros, gold, bitcoin — are competing ledgers, and they can be graded the way an engineer grades any system. Two failure modes matter. Error: how easily false entries can be written into the record. Latency: how quickly and surely everyone can agree on the record’s true state. “Whichever has least error & latency will win” is not a slogan. It is a testable prediction, and this essay will run the test before it ends.
One phrase in that post should be held for later: labor allocation. Money, in his definition, is the system that allocates human work — which is why his 2019 post ends where it does. As automation replaces the work, the system that allocates it fades. The inference is correct as far as it goes. Section five will show what it leaves out.
3. What the ledger is counting
In October 2025, replying to the finance account ZeroHedge, he identified the theory’s foundation:
(”Fiat” is simply the technical term for money a government declares into existence — the dollars in your account.)
Trace any good back to its origin and the same substrate appears. Bread is wheat and an oven: sunlight and heat. Steel is ore and a blast furnace: rock and enormous heat. A day of human work is breakfast converted into effort. Nearly everything in an economy, traced far enough down, is energy that has been transformed — which means that to a first approximation, every price is a price of energy, and the monetary ledger, whatever it is printed on, is tracking claims on energy: who may command how many future joules of the world’s effort.
The following month, on a podcast with the Indian investor Nikhil Kamath, he said it outright: “Energy is the true currency. This is why I said Bitcoin is based on energy. You can’t legislate energy.” The statement is not poetry. It is accounting.
His ZeroHedge reply then explains itself. To print money is to write claims on energy that no energy stands behind — additional tickets to a theater that has not added a seat. Governments in every era have done it, because writing claims costs nothing and confiscation by dilution is invisible. But no government, bank, or empire has ever faked a joule. Energy must be captured, generated, burned; physics audits every claim of its existence instantly and without fee. Claims are free to forge, and the substrate is impossible to forge. That single asymmetry is the monetary problem of the last hundred years, and it implies the shape of the solution: an honest ledger must make writing cost energy.
4. The audit
In 2025 the theory met reality. Through DOGE, the cost-cutting department he ran inside the Trump administration, Musk gained access to the federal government’s actual payment systems, and his dispatches read like an engineer’s incident report on the ledger described in section one. Payment officers who “literally never denied a payment” across entire careers. Payment codes “frequently left blank, making audits almost impossible” — “basically untraceable blank checks.” And a phrase that deserves a permanent place in the monetary vocabulary: “I think we found now 14 magic money computers. They just send money out of nothing... If it was a public company, it would be delisted immediately. It would fail its audit, and the officers of the company would be imprisoned.”
The mechanism, in one of his sentences: “The checks just always clear. The net result is inflation, which is effectively a tax on everyone.” The scale, repeated in the Oval Office, on Rogan, and at the conservative conference CPAC: interest on the national debt now exceeds the entire defense budget. (Several of DOGE’s specific savings and fraud figures were later contested; the structural finding — a ledger with unconstrained, unaudited writes — never was.) His conclusion, delivered after the spending bill passed over his objection, was that the government is “basically unfixable.” Asked whether his new political party would embrace bitcoin, he answered in five words: “Fiat is hopeless, so yes.”
The finding deserves to be read without a party lens. Musk found the fourteen computers while working inside a Trump administration; he left, and the computers remained. They pass, as they have always passed, to the next hands — eventually to hands each reader trusts even less. Whoever you fear most will eventually hold the printer. A ledger no one can corrupt is neither right-wing nor left-wing. It is the only kind that cannot be operated by either side against the other.
5. Why energy cannot be the money itself
The chain to this point: money is a ledger; the ledger tracks claims on energy; the present ledger allows whoever operates it to cheat. The natural conclusion would be to dispense with claims altogether and use energy itself as money. Musk himself speaks this way about the far future — “Money might be measured in terms of wattage”; “I think long term, I think money disappears as a concept” — and in February 2026, replying to the investor Naval Ravikant, he described the endgame in the words that give this essay its title. It is the 2019 clause, as automation++, value of money--, arriving at its destination:

The loop he describes is not a thought experiment; it is a description of his own companies. Tesla builds the energy capture and storage. SpaceX moves the mass. xAI supplies the intelligence, and the robotics program turns intelligence into labor. The monetary philosophy is downstream of the engineering stack — worth remembering whenever the philosophy sounds abstract.
Energy, however, cannot do money’s job, for four reasons, each sufficient on its own. First, it cannot be held. Sunlight not captured this second is gone; batteries discharge; fuel degrades and costs money to store. A savings account denominated in raw energy evaporates.
Second, it cannot change hands cleanly. Settling a grocery bill in joules requires wires, tanks, or trucks; energy is difficult to hand over and more difficult to make change for.
Third, and decisively, it is becoming cheaper on purpose. The future Musk is building — solar capture at planetary scale — makes energy less scarce every year. Savings held in energy would melt precisely as civilization succeeded. It is a ruler that stretches while the measurement is being taken.
Fourth, and least noticed: nobody wants the delivery. Money must be something anyone is content to be paid in, in any amount. Gold qualified because the redemption was itself a prize — scarce, dense, durable, worn as wealth; taking delivery was the point. Energy is pure means. Nobody’s ambitions are denominated in joules — people want the home, the meal, the concert ticket, the machine the joules would power — and one person’s use for delivered energy caps out near a utility bill. Every kilowatt-hour beyond it is a storage burden, not a balance. A money its holders have no desire to actually receive cannot be the thing everyone accepts.
The natural rescue is to store energy as matter and convert between the two as needed. Matter is a stock: a pile that sits and keeps. Energy is a flow: a stream that is used or lost. If the two were freely interconvertible, the stock could hold savings and the flow could settle payments — and Einstein’s equation appears to promise exactly that. Mass and energy are two forms of the same thing, E = mc², at a stupendous exchange rate: one gram of mass is roughly ninety terajoules, enough energy to run a city for a day, in a paperclip.
The difficulty, and the entire theory turns on it, is that the conversion runs in only one direction. Burning a sliver of matter into energy is routine; it is what the sun does every second and what nuclear reactors do every day. The reverse is not. Concentrating energy until particles form yields equal parts matter and antimatter, which cancel each other out. The stock can be burned into flow. The flow cannot be rebuilt into stock. For all practical purposes, the door swings one way.
The July 12 post arrived inside exactly this discussion, and the thread matters. Musk had written that solar power harnessed in space would dwarf the Earth economy. Guillaume Verdon — a physicist whose own company, Extropic, builds computers that compute with thermodynamics — drew the natural inference in the replies: “yes. gdp ~ energy,” adding, “The dyson swarm company will be the most valuable.” The one-unit future, in which energy simply is the measure of value — and the ultimate energy harvester is the ultimate company. Musk, who is building exactly that company, replied: “Necessarily so, as power harnessed would be more than a trillion times what human civilization uses today. The economy will be measured in energy and mass at that point, not dollars.” He conceded the valuation. He conceded the scale. He refused the unit. Pressed on why both, when Einstein’s equation makes them equivalent, he answered with the two sentences this essay opened with:
It is an engineer stating the one-way door precisely: equivalent in principle, separate in practice. The second sentence is the half that almost nobody read. The Sun holds 99.86 percent of the solar system’s mass, and it is a furnace to draw light from, not a quarry to mine. Everything humanity will ever build must come from the sliver of atoms left over.
Read in its thread, the post is not a stray physics remark. It is a correction — offered the one-unit future, energy as the measure of everything, he declined it and insisted on two. The economy of the future has two scarce things, permanently: energy, the flow that cannot be held, and matter, the stock that cannot be stretched. Wattage and tonnage, in his words. Everything that follows in this essay is the consequence of taking that correction seriously — one step past where he stops.
And this carries a consequence for his own prediction that money disappears. Two scarce things that trade against each other must still be priced in something. In the endgame he describes, a solar farm sells power to a robot factory, and the factory turns ore into machines. The farm cannot save its earnings in kilowatt-hours, which are gone by midnight; the factory cannot pay its bills in steel beams. Someone’s savings must hold steady overnight while everything real streams and burns. The trade between the flow and the stock therefore still runs through a third thing — a ledger. Money does not disappear into wattage and tonnage. Wattage and tonnage are the reason something must stand between them.
It is worth being precise about where his own reasoning bends here, because the July 12 post quietly amends his own definition. In 2021 he called money an information system for labor allocation, and on that definition his conclusion follows: remove the labor, and the system has nothing left to allocate — as automation++, value of money--. But the endgame he describes does not eliminate scarcity; it changes which scarcities matter. Even in an economy with no human labor in it at all — machines building machines, the loop fully closed — energy and mass remain scarce, remain different, and remain tradeable against each other, and the trade still requires prices. Labor was never money’s deepest object. Labor was simply the scarcest thing in the world for the whole of human history, and so the ledger spent its history allocating it. The permanent job underneath is allocating scarcity itself. His 2019 clause is therefore half-right in the deepest way: automation retires the labor-money. It cannot retire the scarcity-ledger.
And this deserves to be stated at full strength, because it is the theory’s quiet climax. Money is not a phase civilization passes through. It is a standing consequence of living in a universe whose one substance comes in two states, convertible in only one direction. The man most famous for predicting money’s disappearance has, in a two-sentence reply, supplied the strongest argument yet made that there will always be money.
One further set of his predictions belongs here, because it appears to contradict this conclusion and in fact completes it. Musk predicts that AI and robotics will make goods so abundant that prices fall — deflation within “three years or less” — that governments will respond with universal high income, “via checks issued by the Federal government,” and, in the version that reached the headlines, telling ordinary people: “Don’t worry about squirreling money away for retirement. In like 10 or 20 years it won’t matter.” Read carefully, the retirement claim is about replacing wages — the labor-ledger’s job, which this section just retired. It says nothing about where savings sit while the boom arrives. Carried forward, these predictions describe a printer running harder than it has ever run; his own phrase is that governments “won’t be able to waste the money fast enough.” In a world of abundant goods and an accelerating printer, the one thing that cannot stretch is a ledger with a fixed number of entries. His abundance forecast is not an argument against a fixed ledger. It is the strongest case for one.
6. The instrument the job requires
There is, then, a vacancy at the center of the coming economy: the ledger on which claims on the two scarcities — the flow and the stock — are recorded and priced. The job description follows from everything above, and it has exactly four requirements.
First, the ledger must be impossible to counterfeit: writing an entry must cost real energy, or the claims detach from the joules — fiat’s disease (section three).
Second, it must be impossible to inflate: the number of entries must stay fixed even as energy becomes abundant, or the boom itself melts the savings (section five).
Third, it must be controlled by no one — no company, no government, no founder — or its controller becomes the next printer (section four).
Fourth, it must be checkable by anyone, from anywhere, without vaults or trust, or error and latency return (section two).
The job is ancient, even though the vocabulary is new. A Roman merchant lived in an energy economy — his grain was sunlight, his ships were wind and rowers’ calories, his roads were legionaries’ sweat — and his civilization needed precisely this ledger. What it reached for was gold: not because gold is magic, but because among the materials available it was the hardest to cheat — rare enough that no emperor could conjure it, though they clipped and debased the coinage whenever they could; durable enough not to rot; divisible enough to make change. Gold was never the point. The ledger was the point, and gold was the best writing surface the ancient world had.
Hand that merchant a ledger requiring no vault, impossible to clip, checkable from Alexandria in an instant, and he would not need a day to understand it. He would ask why anyone still carried metal.
What retired gold was not a better metal but an economy that outran it. Trade became fast, global, and finally digital; gold verifies by melting and testing, and settles by physically moving. Civilization did the convenient thing: locked the metal in vaults and circulated paper claims against it. Paper claims, however, are precisely what section three warned about — free to fake. The claims quietly detached from the metal until, in 1971, the pretense was dropped altogether and the claims became pure fiat. The lesson generalizes. In a digital economy, any physical money ends as a vault plus paper, and the paper always wins, and then always cheats. The modern age does not prefer a digital ledger. It requires one.
Seen whole, monetary history is a search for the right material, and every candidate has now been tried. Mass was tried for two millennia: gold, retired by the digital economy. Energy was tried once, directly: in the early 1930s an engineering movement called Technocracy proposed replacing the dollar with certificates denominated in energy; it flared and died, because energy fails as money for the reasons already given — the certificates were claims on a flow that cannot be held, administered by a council of engineers, which is an issuer by another name. And information has been tried twice. Fiat was the first attempt, and this is the fairest thing that can be said for it: the insight was correct. Money’s destiny was information — that is why fiat scaled as gold never could. But the implementation removed the physics — entries free to write, an issuer holding the pen — and a broken information-money is precisely the disorder the audit in section four found running on fourteen computers. Bitcoin is the second attempt: information anchored to both scarcities at once — its writing priced in energy, its supply fixed like mass. The material between the two, respecting both. The idea behind fiat was right. The physics was missing.
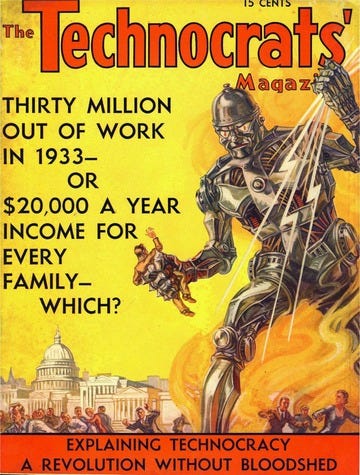
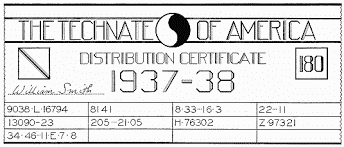
The candidates can now be graded — the test promised in section two. Musk has already graded them himself.
The dollar fails the first requirement by design. Writing costs nothing, and his audit found the fourteen computers that prove it. His grade: “Fiat is hopeless.”
Gold ran the experiment for two millennia and retired exactly as described — in a vault, with paper circulating, and the paper cheating. It fails the second requirement as well: supply grows wherever price rewards digging; slowly, but it answers to price, and bitcoin’s schedule answers to nothing. His grade was aimed at the largest vault of all: “Who is confirming that gold wasn’t stolen from Fort Knox? Maybe it’s there, maybe it’s not.”
One modern proposal deserves its own line: tokens redeemable for energy — kilowatt-hour credits, oil-backed units, state power coupons. Redeemability is the flaw. A redeemable token has a redeemer, and a redeemer is an issuer: someone must hold the energy, honor the claim, and resist the temptation to issue more claims than joules — the full fiat disease, rebuilt at the power plant. An honest energy money cannot be a claim on someone’s energy. It must be a record that costs energy — written into existence by joules already spent, standing behind no one’s promise, communicating prices on its own. No delivery is promised, and none is wanted; the record itself is the asset. Prices as knowledge, exactly as the tradition in this essay’s opening described — carried by a decentralized system that no one has to be trusted to operate.
Other cryptocurrencies fail the third requirement almost without exception. Each has an issuer — a company, a foundation, a founder who granted himself coins before the public could buy in — someone who can be pressured, subpoenaed, or enriched. A printer with a new logo. His grade, delivered under oath in his lawsuit against OpenAI in April 2026: “Some of them have merit, but most of them are scams.”
Dogecoin, the coin he jokes about loving, he filed in a different drawer himself — in a 2021 TIME interview that states this essay’s central distinction in his own words. Bitcoin, he said, “is not a good substitute for transactional currency,” while dogecoin, whose supply inflates forever, is “better suited for transactions” precisely because its issuance encourages spending rather than hoarding. Read what that sorting concedes: the joke coin is for spending, and bitcoin is for holding. Loving the joke coin costs him nothing. The savings question, which is this essay’s question, he had already answered — in 2021, in a national magazine, by process of elimination.
Bitcoin passes all four requirements, and each pass traces to the same two roots: decentralization and physics. The machine, in plain terms, is this. Around the world, computers compete for the right to add the next page of entries to the ledger by expending electricity on a puzzle that is enormously expensive to solve and instant for anyone to check. The software fixes how many new coins each page may create, on a schedule that tapers to zero at twenty-one million, and every participant’s computer independently checks every page against the rules. Energy therefore does not create entries; it seals them. Each page is fastened to all the pages before it by the electricity spent since, so that rewriting history would cost more than any theft could recover — and no coin can come into existence without someone paying for it in joules: “impossible to fake energy.”
Pouring more energy into the network yields no additional coins; it yields a ledger that is more expensive to attack. The coming energy abundance buys security rather than supply, which is the precise opposite of what abundance does to gold.
No one controls it. Its creator, known only by a pseudonym, released the software, vanished within two years, and the fortune of roughly a million coins he mined has never moved — leaving no one to arrest, lobby, or subpoena. And anyone can verify the entire ledger, from the first entry to the newest, with an inexpensive computer and a few days’ patience — on Earth or off it, because verification needs no court, no central bank, and no jurisdiction, a requirement his own multiplanetary project will eventually make literal. It requires no vault, no assay, and no trust.
Here the dead end of section five resolves. Physics forbids converting energy into matter, and yet an economy must make that conversion every day: a solar farm’s earnings must become ore, machines, and land; a factory’s inventory must fund next month’s power. The ledger is where the forbidden conversion takes place — economically rather than physically. Joules are sold and the entries held; entries are spent and tons acquired. The one-way door in the physics becomes a two-way bridge in the ledger, and wattage and tonnage receive the one thing they cannot give each other: a common unit in which to be priced.
The conclusion follows in a straight line. If energy is the true currency, and the currency requires an honest ledger, then a ledger made of energy — its entries priced in unforgeable joules, held by no one, checkable by everyone — is the first money in history that permits true pricing: no claims created from nothing, and no intermediary standing between the saver and the record to skim, censor, or clip the coin. Every money before it embedded a lie somewhere — in the mine, in the vault, in the printer. This one has nowhere to put a lie.
One instrument in existence answers the description, and his strangest sentence can now be read literally: “That is why Bitcoin is based on energy.” Bitcoin is not a rival to energy-money. Bitcoin is how energy becomes money — the flow, written into the only form that does not leak, stretch, or lie.
7. Why the dollar still circulates
If bitcoin fits the job this well, an obvious objection follows: the world still runs on dollars, and almost no one spends bitcoin. The answer is one of the oldest observations in economics, named for a Tudor-era financier. Gresham’s law: when people hold two monies at once, they spend the weaker and keep the stronger. It has held for five centuries: debased coins did the shopping while pure ones disappeared into mattresses. Bad money does the errands; good money does the saving.
The theory therefore does not predict bitcoin coffee purchases. It predicts precisely what is observed: fiat circulating because it is the money people are most willing to part with, and the fixed ledger barely circulating because it is the money people most want to keep. Rare bitcoin payments are not evidence against the thesis; they are Gresham’s law operating in the open. Musk’s own X Money, launched in 2026 on ordinary dollar rails, fits the same pattern. The spending layer remains fiat, while the saving question is answered elsewhere.
It is worth stating the thesis’s actual size plainly. It does not require bitcoin to replace the dollar as the everyday medium of exchange, or as the unit in which governments write their checks. It requires only that the store-of-value and neutral-settlement jobs exist — and that a unit whose supply is a policy is structurally unsuited to them under abundance.
The coexistence has an arithmetic, which should be stated as mechanics rather than advice. The world’s energy pool is growing, and the headroom is almost unlimited — by his own arithmetic, all of Earth’s civilization currently uses “much less than a trillionth” of the Sun’s output. Closing even a sliver of that gap is the entire project Musk is building. A ledger with a permanently fixed number of entries means that each entry, over time, represents a claim on a share of a growing pool. A ledger whose operators keep adding entries means that each represents a claim on a shrinking one. One ruler holds; the other stretches.
A ruler that stretches cannot measure, and this has a consequence that will arrive quietly: once a stable unit exists at scale, the dollar price of bitcoin stops being information about bitcoin and becomes information about the dollar. The two monies can run side by side for a long time — one for spending, one for saving — unless and until the stretching one loses trust altogether.
8. The conduct
If he had truly reached these conclusions, one would expect him to act on them quietly. He did, and the record became visible only this spring.
In 2021 he said it aloud: #bitcoin in his bio, $1.5 billion of Tesla’s treasury moved into bitcoin, cars briefly sold for coin. Then came the firestorm — the only public criticism of bitcoin he has ever made. That May he suspended Tesla’s bitcoin payments over coal-powered mining. The objection was about where the energy came from — never about energy-costed money itself — and it is an objection available only to someone who already understood the instrument as made of energy. The episode taught him the price of plain speech, and the plain speech never returned.
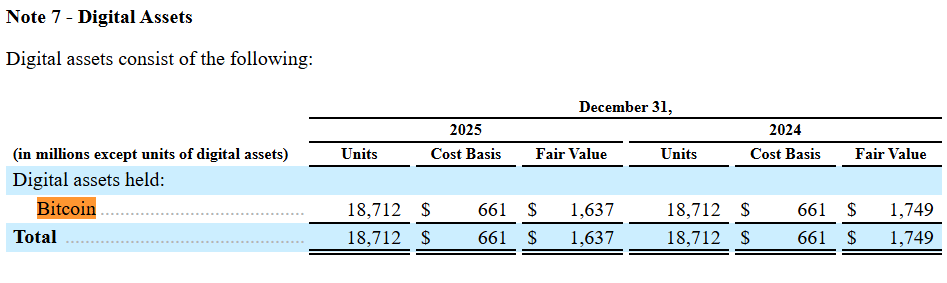
The coins largely stayed. Tesla trimmed a tenth of its position in 2021, sold most of the remainder in mid-2022 when factory shutdowns squeezed its cash, then never sold again and quietly added in early 2025. Tesla holds 11,509 bitcoin today, per its 2026 quarterly filing.
Asked directly about bitcoin at his own shareholder meeting, he answered a different question; an endorsement from that chair moves a trillion-dollar market. And the courtroom sentence from section six — condemning the field, preserving the exception, declining to name it — was the same maneuver performed under oath.
Then, in May 2026, SpaceX filed to go public, and the filing disclosed what no one knew. 18,712 bitcoin — nearly double what anyone believed the company held. Accumulated at an average cost near $35,000 — roughly half of today’s price — through the bear-market years in which the press reported SpaceX had sold. Held untouched since the end of 2024, and carried onto a public company’s balance sheet as a long-term holding. The years of silence explain themselves in a single stroke. Through 2024 he was still buying, and no one announces a purchase they have not finished making — the announcement itself would raise the price being paid. Through 2025 the position was a private company’s secret. The silence was not distance from bitcoin. The silence was execution. Until May 2026, the reading in this essay was an inference from language. Since May 2026, it has been an entry in a federal filing.
The disclosure also has a rational explanation that requires no reading of his mind. A company building toward energy abundance faces a specific balance-sheet problem: its own success expands the energy pool, and every claim it saves in a printable unit weakens as the printer answers the boom. For such a company, holding the fixed ledger is not a speculation on price. It is the recognition that the unit of account and the store of value are coming apart — the divergence section seven described — entered on the books years before the market understood it. The theory does not merely explain his sentences. It explains his treasury.
The fragments were the thesis. The balance sheet is the receipt.
9. Why he will never cheer
He will mention bitcoin; he will not champion it. The distinction is the whole strategy. The most-followed man on earth, holding government contracts and a banking application, openly endorsing a specific alternative to the dollar — that single act would move markets, invite the machinery of the state onto his companies, and hand the story to people incapable of understanding it, who would twist a theory of money into a billionaire pumping a coin. So he states premises and declines conclusions, names the instrument and never blesses it, and the code does its quiet work. It rewards whoever slows down to read it, and it costs him nothing with everyone who does not. Those capable of assembling it were meant to assemble it.
Lay the record end to end a final time. Money is an information system for allocating human time — his words, 2019. The best ledger is the one with least error and latency — his words, 2021. Energy is the true currency, and energy is impossible to fake — his words, 2025. Fiat is hopeless — his words, the same year. The endgame is wattage and tonnage, two scarcities, separate for practical purposes, forever — his words, 2026. And 18,712 bitcoin on his company’s balance sheet, bought in silence and disclosed only when the filing required it — his conduct, all along.
The premises are all his. I have only put them in order and taken the one step he cannot take. He has spent seven years describing a single instrument, from first principles, in public, while leaving the conclusion for the reader. Drawn once, it makes every fragment fall into place.
The paradigm shift
What the reader has just done — stripping money down past the paper, past the policy, past the habits, to what it actually is — is philosophy in the oldest sense of the word. Money is the most successful social construction in human history. It works because everyone agrees to treat it as real, and the agreement runs so deep that questioning it feels like questioning the weather. For a century the construction has drifted further and further from anything physical, until the ledger was defended by nothing except the agreement itself. The fragments assembled here are one man reasoning his way back down to bedrock — time, energy, matter, information — and reporting what money looks like when nothing about it is invented.
Ideas of that kind do not spread by debate. The physicist Max Planck explained why a century ago: a new truth does not triumph by convincing its opponents; it wins because the opponents eventually retire, and a new generation grows up seeing it plainly. The people who operate today’s ledger are not fools, and they are not villains. They are inside the paradigm, and their careers are the paradigm. No argument reaches them, and no argument needs to. Paradigm shifts are not events. They are turnovers — recognition arriving one person at a time until, quite suddenly, it is consensus.
That is why the fragments matter more than they appear to. The most capable engineer alive ran the oldest question in philosophy — what is this thing, really? — against money, in public, for seven years, and arrived exactly where the physics leads. The shift does not require his endorsement, and it does not wait for the textbooks to be revised. It arrives one reader at a time. And the ledger he described runs on through all of it, entry by entry, every ten minutes, as it has since January 2009 — indifferent to who has noticed.
Full sourced record: the 186-item verified timeline anchoring every Musk quotation here — timeline